Buying a Mobile Home in an Alaska Park: Lot Ownership Guide
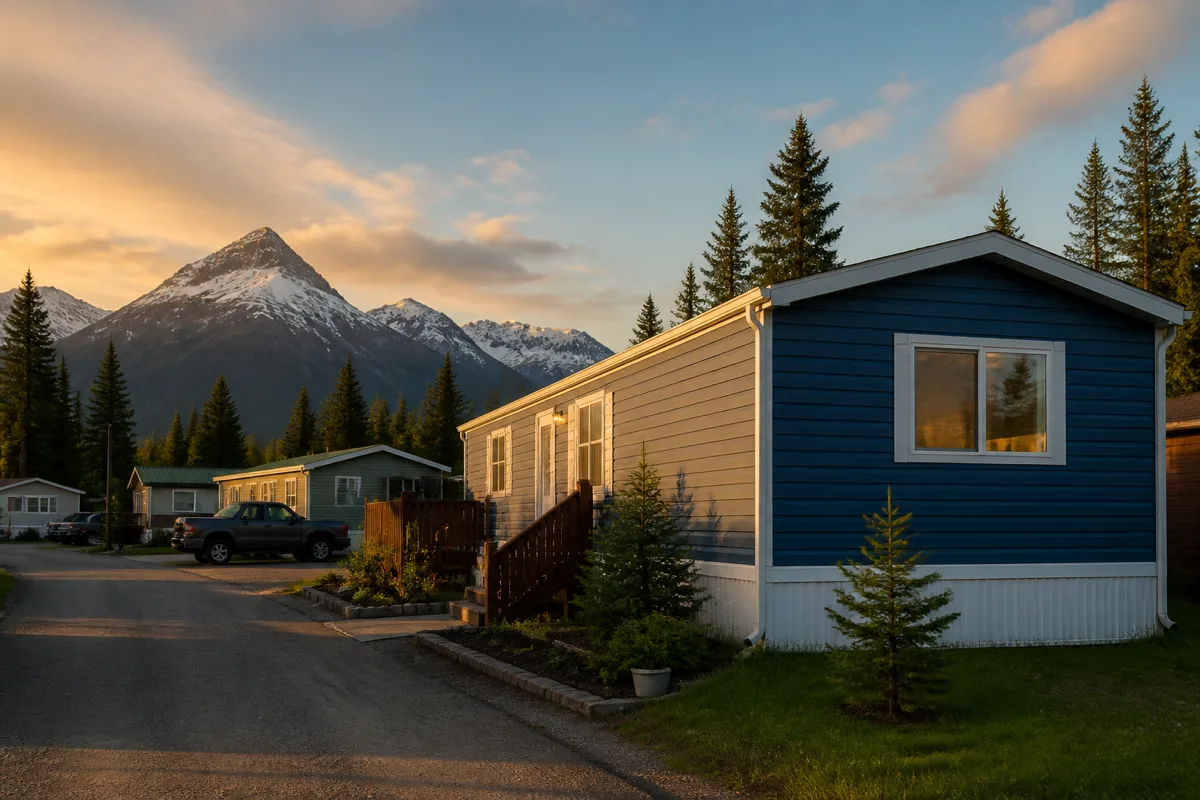
Mobile home parks are a meaningful part of Alaska’s housing stock, especially in the Mat-Su Valley and around Fairbanks, and they offer some of the most affordable path to homeownership in the state. But before you buy a home in a park, one question matters more than almost anything else: do you own the lot underneath it, or are you renting the ground from a park owner?
Two Very Different Ownership Structures
Land-lease (lot rental) parks are the most common structure. You own the manufactured home itself but pay monthly lot rent to the park owner for the ground beneath it, along with access to shared utilities, roads, and sometimes amenities. This is fundamentally different from owning real property — you own personal property (the home) sitting on someone else’s real property.
Owned-lot or resident-owned communities are less common but do exist in Alaska, where either you individually own the lot as real property (sometimes as a platted subdivision lot) or the community operates as a cooperative where residents collectively own the underlying land through shares in the co-op.
The distinction affects almost everything else about the purchase: financing options, long-term stability, resale value, and what happens if the park is ever sold or redeveloped.
Financing Differences
- Land-lease homes are typically financed as personal property with a chattel loan (similar to financing an RV or vehicle) rather than a real estate mortgage, since there’s no real property to secure. Chattel loans often carry higher rates and shorter terms than a comparable mortgage, and government-backed programs have more limited chattel options — see our manufactured home financing guide for how this compares to land-owned manufactured housing.
- Owned-lot manufactured homes — where the home is permanently affixed to a foundation on land you own — can often qualify for a standard real estate mortgage, including FHA and conventional programs, similar to site-built housing. Our manufactured home land loan guide covers that path in more detail.
What to Check Before Buying in a Land-Lease Park
- Lot rent history and increase patterns. Ask the park management for a few years of rent history — a park with a track record of steady, modest increases is a very different risk than one with a history of sharp jumps.
- The lease terms and length. Some parks offer only month-to-month tenancy, which means less long-term security than a multi-year lease agreement.
- Park rules on resale. Some parks require buyers to be approved by management before purchasing an existing home in the park, which can slow down or complicate a sale down the line.
- What happens if the park sells or closes. Alaska statute provides some tenant protections and notice requirements if a park is being converted to another use, but it’s worth understanding those protections (and their limits) before you’re financially committed.
Resale and Appreciation Expectations
Homes on rented lots generally appreciate more slowly — and sometimes depreciate — compared to homes on owned land, since the home’s value is separated from any land appreciation. This doesn’t make it a bad choice, especially for buyers prioritizing lower upfront cost and monthly payment, but it’s worth setting expectations accordingly rather than assuming it will behave like a typical real estate investment.
A Reasonable Starting Point
If you’re comparing a land-lease mobile home against a small site-built home or a manufactured home on owned land, run the full cost comparison — purchase price, financing type and rate, lot rent (which never ends, unlike a mortgage), and expected resale — before deciding. A lender experienced in both financing types can walk through the real numbers with you.
Get pre-approved to understand your budget across all these options. Premier Mortgage (NMLS# 1168048) can help.
Frequently Asked Questions
Can I get a regular mortgage for a home in a land-lease mobile home park?
Generally no — since you don’t own the land, most land-lease park purchases are financed with a chattel (personal property) loan rather than a real estate mortgage.
What’s the difference between a mobile home and a manufactured home?
“Manufactured home” is the modern federal HUD-code term for factory-built homes built after June 1976; “mobile home” is the older, informal term still used colloquially, including for many pre-1976 units that don’t meet current HUD code.
Are resident-owned mobile home communities common in Alaska?
They’re less common than traditional land-lease parks but do exist in some areas — ask a local real estate agent familiar with manufactured housing communities in your target area.
Does lot rent typically go up every year?
It can, though the pattern varies significantly by park. Ask management directly for a rent history before buying, since a pattern of frequent, large increases affects your long-term affordability.
Is buying in a mobile home park a good way to build equity?
It depends heavily on the ownership structure. Owned-lot manufactured homes can build equity similarly to site-built homes; land-lease homes generally build less equity since you never own the underlying land.
Ready to Make Your Move?
Get pre-approved for your home loan first — it gives you a competitive edge. Need a listing agent? We can help.
Or call 9078411600 · or email contact@akhomehq.com
Disclaimer: This article is for informational purposes only and does not constitute financial, mortgage, legal, or tax advice. Interest rates, loan programs, eligibility requirements, and fees are subject to change without notice and may vary based on your individual circumstances. Alaska Home HQ is not a lender, broker, or financial institution. All loan applications are processed by Premier Mortgage (NMLS: 1168048). We may have a business relationship with Premier Mortgage and may receive compensation when you use their services through our links. Consult a licensed mortgage professional before making financial decisions. Terms of Service · Privacy Policy