Financing a Barndominium in Alaska: What to Know
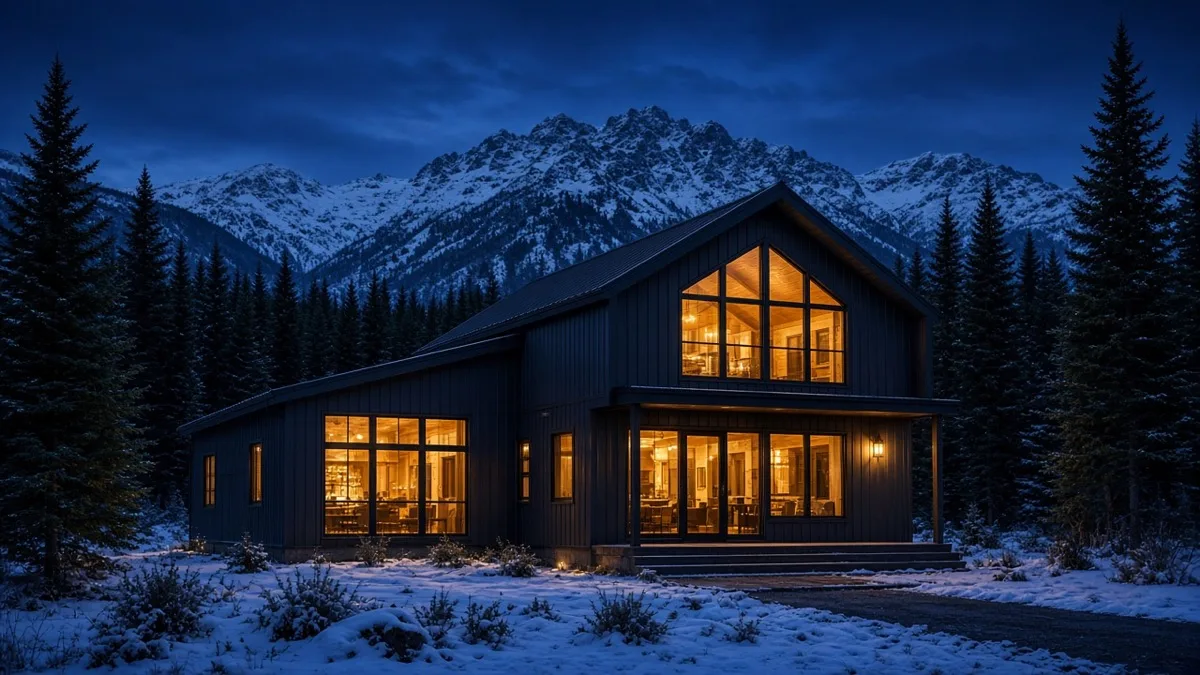
Barndominiums — post-frame or metal-sided structures combining living space with garage, shop, or barn area — have grown popular in Alaska for buyers who want durable construction, flexible floor plans, and lower per-square-foot build costs than traditional stick framing. But financing one is more complicated than financing a conventional home, and Alaska’s climate adds its own wrinkles.
Why Barndominiums Are Harder to Finance Than Standard Homes
Conventional and government-backed loans require the appraiser to find comparable sales of similar properties. In most Alaska markets, barndominiums are still uncommon enough that appraisers struggle to find true comps — they often end up using site-built home comparables with adjustments, or a mix of pole-barn and residential comps, which can produce a more conservative value opinion than the actual construction cost.
Lenders also scrutinize whether the structure meets the loan program’s definition of a “residential dwelling.” A barndominium with a large unfinished shop area attached to the living space may need the living space clearly delineated, permanently affixed to a foundation, and built to residential code — not just agricultural or pole-barn standards — to qualify for standard mortgage financing rather than a commercial or agricultural loan.
Financing Paths That Typically Work
- Construction-to-permanent loans are usually the most realistic path for a new barndominium build, converting to a standard mortgage once construction is complete and a final appraisal confirms value.
- USDA Rural Development loans can sometimes work for barndominiums in eligible rural Alaska areas, provided the structure meets USDA’s property standards for a residential dwelling.
- Portfolio or non-conforming lenders may offer more flexibility than a standard conventional loan if the property doesn’t fit neatly into Fannie Mae or Freddie Mac guidelines, though terms and rates can be less favorable.
- Conventional financing on an already-completed, code-compliant barndominium is possible once it’s built and appraised, especially if similar structures have started selling in the area and comparable sales data improves.
What Lenders and Appraisers Want to See
Documentation matters enormously here. Have your builder provide engineered plans, a clear breakdown of finished living square footage versus shop or storage area, and confirmation the structure will meet local building code and permitting requirements. In Alaska specifically, insulation values, foundation design suited to frost depth, and ventilation to manage condensation in a metal structure are all things an appraiser or underwriter may ask about.
The Fannie Mae Selling Guide doesn’t prohibit unconventional construction types outright, but requires appraisers to address any unique or atypical construction and support the value opinion with adequate market data — which is the real friction point for barndominium financing in a market where they’re still relatively rare.
Planning Your Alaska Barndominium Project
If you’re building rather than buying an existing barndominium, talk to a lender before you finalize plans with your builder. A construction-to-permanent loan structure needs to be arranged in advance, and knowing your financing constraints early can shape decisions about finished square footage, foundation type, and how much of the structure is dedicated to living space versus shop or storage. Comparing this path to a more standard construction-to-permanent loan or a traditional FHA loan in Alaska can help clarify which route fits your project and budget.
Frequently Asked Questions
Can I get an FHA loan on a barndominium in Alaska?
It’s possible if the structure meets FHA’s minimum property standards and comparable sales support the appraised value, but this is decided case by case and not every lender or appraiser will be comfortable with the property type.
Why is the appraisal the biggest hurdle for barndominium financing?
Because appraisers rely on comparable sales, and barndominiums are still uncommon in most Alaska markets, appraisers often have to use imperfect comparables and apply larger adjustments — which can result in a value opinion lower than actual construction cost.
Does the shop or garage portion of a barndominium count toward the appraised value?
Typically, only the finished, code-compliant living area is valued as residential space. Attached shop, garage, or storage areas are usually valued at a lower per-square-foot rate, similar to how a garage is valued in a standard home appraisal.
Is a barndominium harder to insure in Alaska?
Some insurers are less familiar with metal or post-frame residential construction and may require specialized coverage or charge different rates than for a conventional stick-built home. Shop around and disclose the construction type clearly when getting quotes.
What foundation type works best for a barndominium in Alaska’s climate?
This depends on soil conditions and frost depth at your specific site — a licensed engineer familiar with Alaska foundation requirements should design the foundation, since standard pole-barn footings often aren’t sufficient for year-round residential use in cold climates.
Planning a barndominium build or purchase in Alaska? Get a free home loan quote from Premier Mortgage (NMLS# 1168048) to understand your financing options early.
Ready to Take the Next Step?
Get a free home loan quote today through our trusted partner.
Or call 9078411600
Disclaimer: This article is for informational purposes only and does not constitute financial, mortgage, legal, or tax advice. Interest rates, loan programs, eligibility requirements, and fees are subject to change without notice and may vary based on your individual circumstances. Alaska Home HQ is not a lender, broker, or financial institution. All loan applications are processed by Premier Mortgage (NMLS: 1168048). We may have a business relationship with Premier Mortgage and may receive compensation when you use their services through our links. Consult a licensed mortgage professional before making financial decisions. Terms of Service · Privacy Policy