Valdez Alaska Home Loans for Pipeline Towns
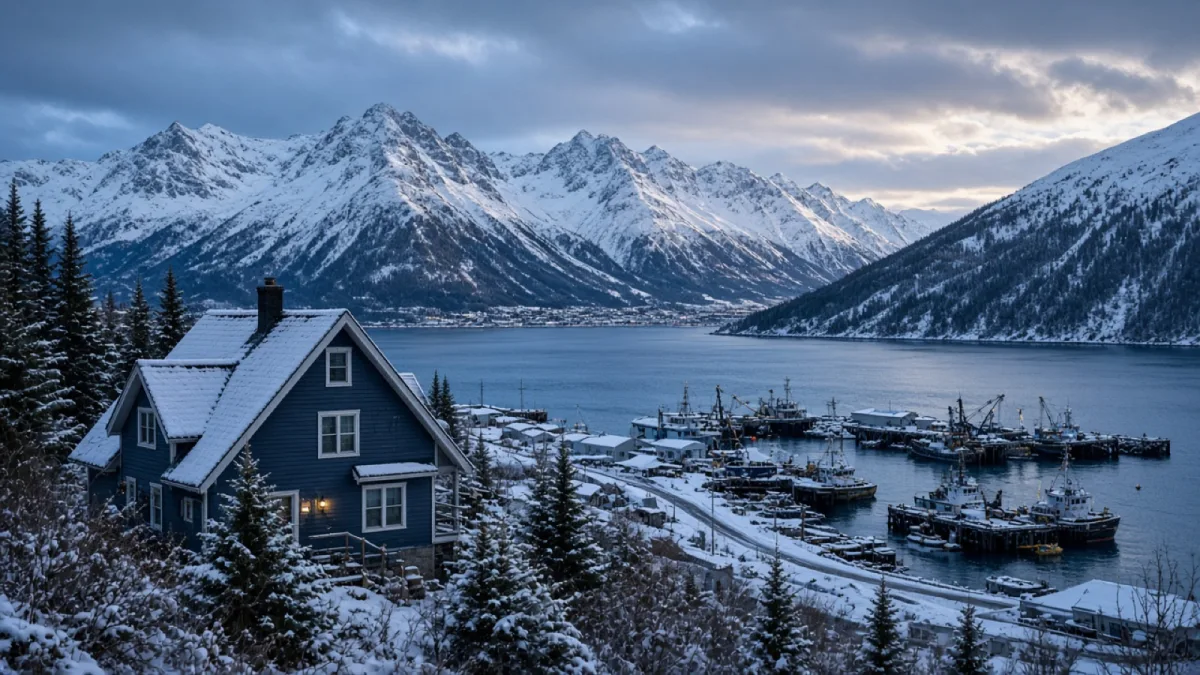
Valdez Alaska home loans have to underwrite a pipeline town that also runs on summer tourism: rotational oil-and-gas pay, short winter access windows, and a housing stock squeezed between the water, the mountains, and avalanche and flood overlays. The programs are familiar — conventional, FHA, VA, USDA — but the file is a Prince William Sound file, not an Anchorage cul-de-sac file.
You may qualify for more than one path. Rates vary. Loans are subject to credit approval. Alaska Home HQ is not a lender.
Valdez Alaska Home Loans: What Makes the File Different
Valdez sits at the southern end of the Richardson Highway and the trans-Alaska pipeline marine terminal. Work is a mix of Alyeska and contractor rotations, port and city jobs, school and hospital W-2s, and a summer tourism spike (cruises, fishing, glacier traffic).
HUD’s current published median family income for the Chugach Census Area is $114,600 (HUD income limits). That is the federal statistical area that includes Valdez after the old Valdez-Cordova split. It is a household-income benchmark, not an appraisal of a hillside house above the harbor.
Underwriting pressure points:
- Rotational and overtime pay. Oil-and-gas schedules can look like two years of strong W-2s with wild monthly spikes. Lenders average. A single fat overtime year may be discounted. See oil and gas industry mortgages.
- Seasonal tourism income. Two years of returns, a trend, and reserves — same as other Alaska seasonal files (seasonal income).
- Thin comps. Unique views and snow-load roofs do not always have three closed sales. Appraisal gaps happen even when the list price looks reasonable on a statewide spreadsheet.
- Winter access. Thompson Pass and avalanche control can delay appraisers, inspectors, and you. Do not copy a 21-day Anchorage close.
Valdez does not have its own AK Home HQ city page. For a coastal comparison market, see Homer and the Valdez real estate guide.
Conventional, FHA, VA, USDA — and Where AHFC Fits
| Program | When it often fits | Valdez watch-outs |
|---|---|---|
| Conventional | Stable W-2, standard dwelling | 3% products need current published 80% AMI; heat/foundation overlays |
| FHA | Lower down payment | Property standards; flood/avalanche insurance bindability |
| VA | Eligible veterans, including pipeline-era service | Residual income; still a full property review |
| USDA | Many addresses map rural | Income caps; confirm the specific parcel |
AHFC rural and first-lien products are state programs. They can matter in a small town when a GSE overlay fails a rural feature. Premier Mortgage (NMLS# 1168048) does not originate AHFC loans. If you need a state rural or Uniquely Alaskan box, use an AHFC-approved lender. If you want conventional, FHA, VA, or USDA, that is the quote path Premier can run.
USDA is not “Valdez is rural so you automatically qualify.” Use the current USDA maps and income limits. Our USDA eligible areas piece is the process, not a substitute for the address tool.
For 3% conventional, look up the tract in Fannie’s AMI tool. HomeReady/Home Possible are compared here. Dual pipeline households often clear 80% AMI even when a single school-district W-2 does not.
Rotational Pay, Per Diem, and What Counts
Bring the last two years of W-2s, a current LES or paystub series, and a written rotation schedule if you are hitch-based.
- Base plus scheduled overtime that shows a two-year trend is usable more often than a one-off turnaround bonus.
- Per diem and travel may be excluded if they are expense reimbursements, not pay. Do not count per diem in your head if the underwriter will strip it.
- Layoff between hitches needs an explanation and, ideally, a return-to-work pattern.
- A spouse with local year-round income (hospital, school, city) often does more for DTI than another letter from the contractor.
If you are 1099 on a specialty crew, you are in self-employed land (self-employed mortgages). Two years of returns beat a verbal “next hitch is guaranteed.”
PFD deposits can help cash to close once they are in the bank. They do not replace reserves when Thompson Pass closes and you stay in a hotel.
Winter Access, Snow Load, and Insurance
Valdez snow is not a cute statistic. It is a roof, driveway, and insurance fact.
- Appraisers and inspectors need a safe window. Build extra days into the contract.
- Snow-load and roof condition show up on appraisals — see snow load appraisal.
- Flood and slide overlays can require insurance the quote did not include. Bindability can be a loan condition.
- On-site wastewater still follows 18 AAC 72, including commonly applied 100-foot well-to-septic horizontal separation. Coastal and alluvial soils can make that design expensive.
City water/sewer pockets are simpler files than a well-and-septic lot at the edge of town. Say which one you are buying when you apply.
How to Sequence a Valdez Purchase
- Disclose rotation or seasonal income on day one of pre-approval.
- Order appraisal and inspection with winter slack.
- Keep financing and appraisal contingencies unless you are cash.
- If the house is unconventional (heat, foundation, access), do not force a 3% conventional overlay — change the house or change the program.
Ready to see what you may qualify for? Get a free home loan quote from Premier Mortgage (NMLS# 1168048). Rates vary; subject to credit approval. Premier originates conventional, FHA, VA, and USDA — not AHFC state programs.
Frequently Asked Questions
Can rotational pipeline pay qualify for a Valdez mortgage?
It may, when two years of W-2s show a usable average and the lender can separate base pay from one-time bonuses or per diem. A single high overtime year is often discounted. Guidelines vary and are subject to credit approval.
Is USDA a good fit for Valdez home loans?
Many Valdez-area addresses map as rural, but USDA has income and property tests. Confirm the current map and household income limits. It is not automatic because the town feels remote.
How do winter road closures affect closing?
Thompson Pass and weather can delay appraisers, title work, and travel to the signing table. Use longer contract timelines than Southcentral defaults and keep reserves for lock extensions. Remote online notarization, when allowed, still does not move the appraiser.
Does AHFC rural financing replace USDA in Valdez?
They are different programs. AHFC rural products are state loans through AHFC-approved lenders. USDA is a federal guarantee or direct program. Premier Mortgage (NMLS# 1168048) does not originate AHFC. Price USDA/conventional/FHA/VA separately from any state rural reservation.
Can I use a VA loan if I work in Valdez but am not stationed there?
If you have VA eligibility and the home will be your primary residence, you may qualify. Employment location is not the same as entitlement. Property standards and residual income still apply. Check VA.gov for current rules.
Ready to Take the Next Step?
Get a free home loan quote today through our trusted partner.
Or call 9078411600
Disclaimer: This article is for informational purposes only and does not constitute financial, mortgage, legal, or tax advice. Interest rates, loan programs, eligibility requirements, and fees are subject to change without notice and may vary based on your individual circumstances. Alaska Home HQ is not a lender, broker, or financial institution. All loan applications are processed by Premier Mortgage (NMLS: 1168048). We may have a business relationship with Premier Mortgage and may receive compensation when you use their services through our links. Consult a licensed mortgage professional before making financial decisions. Terms of Service · Privacy Policy